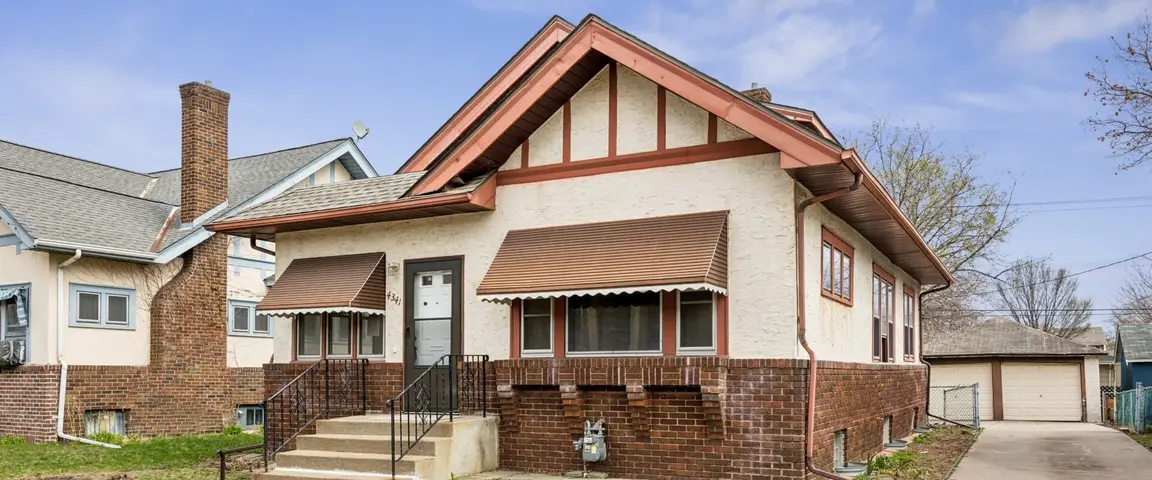
A one-bedroom condo in Minneapolis sold for $40,000, and for a while the county kept every dollar. The owner was 94. Her tax debt had grown to about $15,000 once penalties, interest, and costs piled onto the original bill, and her case went all the way to the United States Supreme Court. In May 2023 the justices ruled against Hennepin County without a single dissent. If you’re behind on property taxes anywhere in Minnesota, that ruling is part of your story too. I’ve bought houses from owners in that spot, and most had more runway than they thought.
Is Minnesota’s Property Tax System Fair to Homeowners?
Losing a home’s whole equity over a much smaller tax bill was never defensible, and it took the Supreme Court to make that official.
Minnesota’s forfeiture system sounds tidy on paper. Pay your taxes or the state takes the parcel, with no lender involved. Title moves to the State of Minnesota, and the county sells the property later.
Under the old version of the law, the county kept whatever that later sale brought in, so a homeowner with real equity walked away with nothing. Tyler v. Hennepin County ended that. The Court held that keeping the value above the tax debt was a taking under the Fifth Amendment.
So is the system fair now? It’s better, though I wouldn’t call it fair yet. Assessed values climb with the market whether or not your income does, and a retiree in Nokomis or a duplex owner in Frogtown feels that squeeze long before any notice shows up.
Timing trips up most people I meet, since their clock started years earlier with one unpaid half-payment. By the time a certified letter arrives, penalty, interest, and costs have stacked on the original bill and the math has turned ugly.
Where Minnesota’s Property Tax Rules Hit Owners Hardest
An out-of-state heir called me last year about a small rambler in Fridley. He’d flown in for a weekend, gotten one contractor estimate on the kitchen, and learned the job would cost more than it could ever add to the house. Meanwhile the back taxes kept climbing. If you’re holding a house like his, here’s how we buy houses in Fridley MN in all situations.
Inherited property is where property tax foreclosure bites hardest. Heirs scatter across states, and notices go to an address nobody checks while siblings argue about whether to keep the place.
Rentals and inherited homes also pay a steeper late penalty. Under Minnesota law, the late-payment penalty on a homestead tops out at 8 percent, while non-homestead property can reach 12 percent. Once an inherited house loses its homestead classification, charges pile up faster than heirs expect. Your county statement shows the schedule that applies to you.
Fixed-income seniors get squeezed too. The state runs a Senior Citizens’ Property Tax Deferral Program for homeowners 65 and older who meet income and equity limits, so check the current terms with the Department of Revenue.
Earlier, plainer notice would help more than any rate change. A letter saying “you are 14 months into a clock that ends in forfeiture” beats a lien notice nobody outside a courthouse can read.
The Minnesota Forfeiture Timeline in Order
Tax forfeiture and mortgage foreclosure run on two separate legal tracks, handled by two different offices, and one Minnesota homeowner can be caught in both at once.
For most property, taxes come due in two halves, on May 15 and October 15. Miss one and late penalties start right away. Whatever’s still unpaid goes delinquent on the first business day of the next January.
Your county then files the delinquent list with district court. A judgment is entered, and the parcel is bid in for the State of Minnesota. The Minnesota Department of Revenue’s tax forfeiture manual sets May 11, 2026 as the start of this cycle’s redemption period for property under court judgment. Every later deadline runs from that date.
Three years is the standard redemption window, though a few properties get less. Most non-homestead parcels in a “targeted community,” as state law defines it, get one year. Certain municipal solid waste disposal facilities also get one year, and abandoned property can drop to five weeks after a court order.
Near the end, the county sends a Notice of Expiration of Redemption by certified mail. Carver County’s delinquent tax page describes the next step: the list of parcels set to forfeit runs in the county newspaper for two weeks.
Partial payments won’t stop forfeiture unless the full amount gets paid or you sign a confession of judgment, which is Minnesota’s installment plan for delinquent property tax. Most property gets 10 years to pay and commercial property gets five, but missing a payment by more than 60 days puts the parcel back on the forfeiture track.
If you decide the house has to go, you usually have months to sell on your own terms. That’s where a direct buyer like K&G Investments can close before the clock runs out.
What Is Property Tax Foreclosure in Minnesota?
People say “foreclosure” for two very different events here, and mixing them up costs owners money.
What most people call property tax foreclosure is legally tax forfeiture. It transfers absolute title to the State of Minnesota for unpaid property taxes. No lender files anything, and there’s no sheriff reading a legal description aloud in a hallway.
Mortgage foreclosure is different. A lender enforces its lien, usually by advertisement under Minnesota statutes chapter 580, and the county sheriff runs the sale. Chapter 581 covers foreclosure by action, and chapter 582 holds general rules for both.
After forfeiture, the county usually sells the parcel to get it back on the tax rolls, which is why Hennepin, Olmsted, and St. Louis counties all post tax-forfeited land lists. After a sheriff’s sale, the winning bidder holds a certificate and waits out a redemption period before getting the deed.
Can you still sell during either process? Generally, yes. A sale that pays off the delinquent property tax at closing stops a property tax foreclosure cold, because the state’s claim disappears with the debt.
People sometimes tell distressed homeowners to wait for the auction and see what happens. I think that’s backwards. Waiting hands your equity to whatever a later sale brings, when you could have set the price yourself months earlier.
How Can Minnesota Reform Its Property Tax System to Be More Fair and Equitable?
“The Supreme Court already fixed this, so why worry?” I hear that a lot, and it’s half right.
Tyler v. Hennepin County settled a narrow question about surplus value, and it didn’t shorten any deadline or lower any penalty. Minnesota rewrote its forfeiture law in response, with a surplus claim process that took effect July 1, 2024. After a forfeited parcel sells, the county auditor mails a claim form by certified mail to people with an interest in it, and they have six months from that first mailing to file.
Real reform would go further. I’d start with plain-language notices that put the forfeiture date in a box at the top, plus a housing counselor referral in the first delinquency letter. The mortgage side of Minnesota law already does something close, since lenders on owner-occupied homes must send a counseling notice before they record a notice of pendency.
My mild heresy is that the three-year window is plenty generous. The clock’s length was never the problem. Most people don’t know it exists until year two and a half, and by then the added costs make redemption harder than selling.
What Does the Minnesota Foreclosure Sale Process Look Like?
Forget the courtroom and the crowd of bidders. In my experience a sheriff’s sale is a few people in an office on a weekday, and it’s over in minutes.
Minnesota law puts the sale in the hands of the sheriff or a deputy, held in public to the highest bidder in the county where the property sits, between 9 a.m. and 4 p.m. The lender’s attorney usually opens with a credit bid for the loan balance, and most of the time nobody outbids it.
You can stay in the house through the redemption period, since the winning bidder isn’t the owner yet. Many homeowners never hear about one option in the Minnesota Attorney General’s foreclosure guide: filing an Affidavit of Postponement delays the sheriff’s sale by five months. Your redemption period afterward shrinks to five weeks.
Think hard before you file it. Five extra months in the house sounds great in November, while five weeks of redemption in April is a very short runway for a sale. The median Minnesota home took 36 days to sell in August 2026, according to Redfin’s state market data, and that doesn’t count closing time.
If you plan to sell, the longer redemption window is worth more than the delay.
How Do You Search a Minnesota Sheriff’s Foreclosure Sales Database?
Hennepin County runs an online mortgage foreclosure search covering sheriff’s sales from the past 12 months. The sheriff’s office says plainly that it has no list or calendar of scheduled sales, so it won’t help you find a future sale date.
Scheduled sales appear in the county newspaper’s legal notices for six weeks before the sale.
Tax-forfeited parcels sit on separate county land lists, but as a homeowner you probably don’t need any database. You want your own parcel record from the county, which shows the tax years outstanding, the judgment status, and the amount to redeem. A quick call to the property tax office gets you a payoff figure good for that day.
Can You Redeem a Property After Foreclosure in Minnesota?
How much time do you really have left?
That depends on which track you’re on. After a sheriff’s sale, most Minnesota mortgage foreclosures carry a six-month redemption period. Some carry twelve months, such as certain farm property, and abandoned homes or owners who filed a postponement get five weeks. Your published foreclosure notice names your period.
To redeem after a sheriff’s sale, you pay the amount bid at the sale plus interest and allowed costs. The Attorney General’s guide notes you can also refinance or sell during this window.
On the tax side, redeeming means paying the delinquent taxes, penalties, interest, special assessments, and fees before the redemption period expires.
Even after forfeiture, the door isn’t always locked. Minnesota still lets some former owners repurchase a forfeited parcel, though the county board has to approve it and the window is short. The county auditor’s office can tell you whether that applies to your property.
I keep seeing the same pattern. People who could redeem through a sale wait until the final sixty days, then learn a typical buyer needs an appraisal, a lender, and a title commitment. That’s often when we get the call. K&G Investments buys with cash and no financing contingency, which is why those late closings can still land in time. If you’d like to know who you’d be talking to, you can meet the team behind K&G Investments.
Where Is the Minnesota Foreclosure Sales Office Located?
In Hennepin County, written redemption requests go to the Hennepin County Sheriff at 350 South 5th Street, Room 190, Minneapolis, MN 55415. Sales run on weekdays at the time printed in the published notice, and the sheriff’s foreclosure sales page has current contact details.
Redemption money goes to Room 30 in the same building, on business days between 9 a.m. and 4 p.m. The office takes a wire, a cashier’s check payable to the Hennepin County Sheriff, or cash. Personal checks won’t work.
Other counties set their own hours and procedures, so call your county sheriff before you drive anywhere.
There’s no single Minnesota Foreclosure Sales Office at the state level. Instead, the state has 87 county sheriff’s offices running mortgage foreclosure sales and 87 county offices running tax forfeiture.
What Services Does the Foreclosure Sales Office Provide?
The sheriff’s civil unit runs the sale, issues the certificate of sale, and processes redemptions. In Hennepin County, a homeowner redeeming starts with a written request by mail or in person, plus a $250 fee. The office asks for that request seven to ten days ahead, since staff need time to calculate the amount.
Creditors have their own lane. A junior lienholder files a recorded notice of intent to redeem, a recorded copy of the lien, and any recorded assignments, at least a week before the owner’s period ends.
What the office won’t give you is advice. Deputies won’t tell you whether redeeming is smart, and they won’t review your numbers. For strategy, talk to an attorney or a housing counselor. The Minnesota Homeownership Center offers foreclosure help free of charge.
Nobody will chase you, either. No one calls to say your redemption expires Friday, and once the deadline passes, the certificate becomes the new owner’s deed.
Want a second set of eyes first? We’re happy to compare what a sale nets you against what redemption costs, at no charge. Plenty of homeowners we’ve talked with kept their house. You can contact our team whenever it suits you, with no pressure either way.
How Do Jail and Warrant Records Tie Into Minnesota Foreclosures?
A seller’s open warrant won’t gum up a closing. Criminal records and foreclosure records live in separate systems, and the same sheriff running your sale and the jail is an org chart coincidence.
One real overlap exists. If a party to a foreclosure is in custody, the sheriff still has to serve the paperwork, and that can slow a timeline a bit.
Criminal judgments are a different matter. A restitution order in Minnesota gets docketed as a civil judgment, and that judgment becomes a lien on real property in the county. It shows up on a title search and has to be cleared at closing, like a contractor’s lien. Arrest records don’t, and we’ve closed with sellers who were sure their past would sink the sale.
Do Gun Permits Affect Minnesota Foreclosure Sales?
A seller in Brooklyn Park once waited two months to call me because he’d heard his permit to carry showed up in the county’s property file. It doesn’t, and the wait cost him two months of interest. If you own a home there, start with our page for cash home buyers in Brooklyn Park MN.
County sheriffs issue permits to carry under state law, which is the only reason the topic shares a website with foreclosure sales. Permit data sits apart from property records, and no title examiner pulls it.
Guns do come up when families sell inherited houses, since firearms left in a closet or safe are personal property to handle before closing. A probate attorney or an FFL dealer can sort out what’s legal for an heir out of state. I once found a locked gun safe in a Coon Rapids basement, and a locksmith got it open.
What Role Does Water Patrol Play in Minnesota County Offices?
Water patrol has nothing to do with your foreclosure. State law puts each county sheriff in charge of patrol and rescue on local waters, so the agency selling foreclosed homes in Crow Wing County also runs boats.
Lakeshore property does carry one real wrinkle. Shoreland rules, set by the DNR and enforced through county zoning, can limit rebuilding and septic placement. Thinking about a foreclosed cabin in Crow Wing or Otter Tail County? Call the county zoning office before you bid, because a nonconforming cabin that can’t be rebuilt after a fire is a very different buy than the listing suggests.
What Actually Matters If You’re Facing Foreclosure in Minnesota
The redemption window is the part people misunderstand most. You still own the home during redemption, and you can live in it or sell it. That’s how many of our sellers in Anoka, Dakota, and Washington counties walk away with equity.
What you can’t do is wait, because every month adds interest, attorney fees, and sheriff’s costs to your redemption amount. On the property tax side the clock is longer, though penalties and interest keep growing the whole time.
If there’s equity in the house, selling before or during redemption usually beats letting the clock run out. If there isn’t, a short sale or a deed in lieu may be possible, and your lender’s loss mitigation department is the first call.
Frequently Asked Questions
Does a sheriff’s sale show up on my credit report? The foreclosure does, and it typically stays for seven years from the first missed payment that led to it. Selling before the sale can keep a completed foreclosure off your report.
Can I sell my house after the sheriff’s sale has already happened? Yes, during the redemption period. The sale has to bring in enough to pay the redemption amount, so the sooner you start, the better your odds.
Will a buyer find out my home was in foreclosure? The notice of pendency and the sheriff’s certificate are public records, so a title search will show them. That doesn’t stop a sale, and it doesn’t change what we pay.
Do I owe the difference if the house sells for less than I owe? Minnesota law bars a deficiency judgment after a foreclosure by advertisement with a six-month or five-week redemption period. Foreclosure by action follows different rules, so talk to an attorney about your file.
How fast can a cash sale close in Minnesota? Usually seven to fourteen days once title comes back clean. Recording times and any judgment payoffs set the floor.
Does a property tax foreclosure work the same way? No. Tax forfeiture has no sheriff’s sale. It runs on the county’s redemption clock, usually three years, and paying the full amount before that clock expires ends it.
If you’re somewhere in this process and want a straight answer about what your house is worth and how much time you have, reach out. There’s no obligation, and if selling isn’t the right move for you, we’ll say so.